Selling
UAD 3.6: How the New Appraisal Standard Changes a Hawaiʻi Island Home Sale
 By Carol Porter, Realtor® · June 15, 2026
Beginning November 2, 2026, all new appraisal reports submitted through the system used by Fannie Mae and Freddie Mac must use UAD 3.6, the redesigned Uniform Appraisal Dataset, and a new report format called the Uniform Residential Appraisal Report (URAR). A new appraisal submitted in the old format after that date will be rejected.
That may sound like an industry change that sellers shouldn’t have to think about. But on Hawaiʻi Island, it may matter more than you would expect. Our properties often don’t fit neatly into the conventional mainland model of one house on one suburban lot. We have ʻohana units and ADUs, multiple structures, photovoltaic systems, unusual site characteristics, distinctive views, acreage, and homes that have evolved over decades. UAD 3.6 gives appraisers a much more detailed and standardized way to describe those characteristics.
For sellers, the practical lesson is straightforward: make it easy for the appraiser to understand exactly what your property is.
What Is UAD 3.6?
The Uniform Appraisal Dataset establishes how property information is reported in appraisals submitted to Fannie Mae and Freddie Mac. For years, that information has been squeezed into a collection of familiar numbered forms, including the 1004 used for many single-family homes. Additional information that didn’t fit neatly into those forms often ended up in narrative comments and addenda.
UAD 3.6 replaces that system with a dynamic reporting structure that adapts to the property and type of appraisal. Instead of simply providing more boxes to check, the new report collects much more structured information about the dwelling, site, condition, improvements, accessory units, outbuildings, energy features, views, and other characteristics.
The appraiser’s fundamental job has not changed. The appraiser still develops an independent opinion of market value based on appropriate appraisal methods and market evidence. What changes is the level and organization of the information used to describe and support that analysis.
Why Does This Matter on Hawaiʻi Island?
Hawaiʻi Island has an unusually diverse housing stock. Two homes with similar square footage may be very different properties once you consider the site, additional structures, views, improvements, utilities, energy systems, condition, and permitted uses.
That makes a more flexible appraisal format potentially useful here. Instead of forcing a complicated property into a relatively rigid national form, UAD 3.6 provides a more detailed framework for describing what is actually there.
Consider an ʻohana, ADU, converted living area, or second structure. The new format provides considerably more structured information about accessory dwelling units and other improvements. If your property includes one, gather the permits and other records that establish what was approved and how the improvement is documented. Don’t make the appraiser reconstruct that history from incomplete information.
The same principle applies to renovations. If you substantially remodeled a kitchen, replaced a roof, upgraded electrical or plumbing systems, or completed other significant work, keep records of what was done and when. An appraiser doesn’t simply add the cost of improvements to the value of a house, but accurate documentation helps the appraiser accurately describe its condition and improvements.
Hawaiʻi Views Get a More Nuanced Description
This may be one of the more interesting changes for Hawaiʻi Island.
Under the previous UAD standard, the way an appraiser reported a view was relatively limited. UAD 3.6 allows the appraiser to identify multiple types of views and provide more information about them, including whether a view is full or partial, whether it is the property’s primary view, and whether its market impact is beneficial, neutral, or adverse.
That distinction can be meaningful here. “Ocean view” can describe everything from an expansive, unobstructed coastline and ocean panorama to a narrow strip of blue visible between two neighboring houses. A property may also have combinations of ocean, coastline, golf course, mountain, or other views.
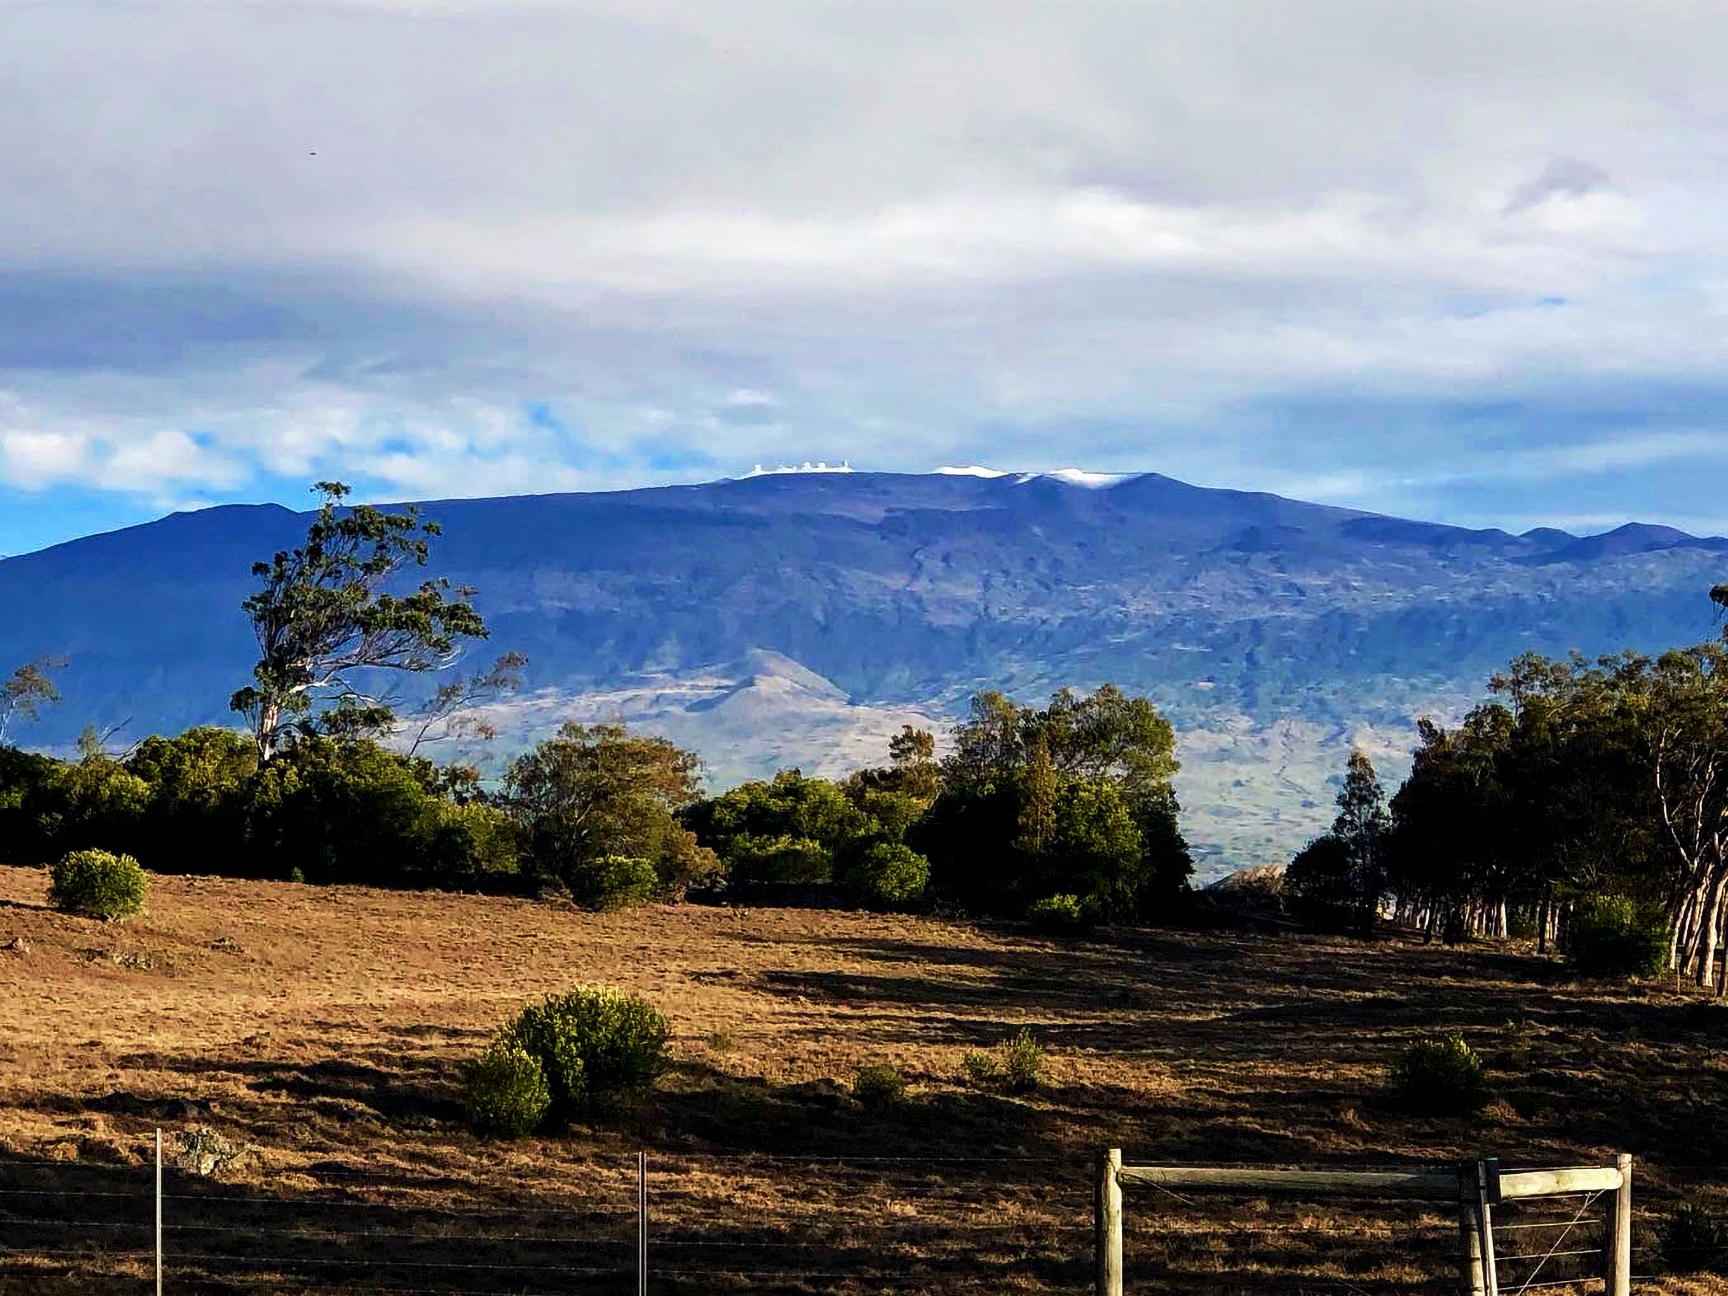
UAD 3.6 does not automatically assign additional value to a better view. The appraiser still has to determine from market evidence whether buyers pay more for that characteristic and, if so, how much. But the new report provides a much better framework for describing the view being valued.
Site influences are treated more precisely as well. That additional detail can be particularly useful in a market where site characteristics can vary dramatically within relatively short distances.
What About Solar?
Photovoltaic systems are another obvious Hawaiʻi example.
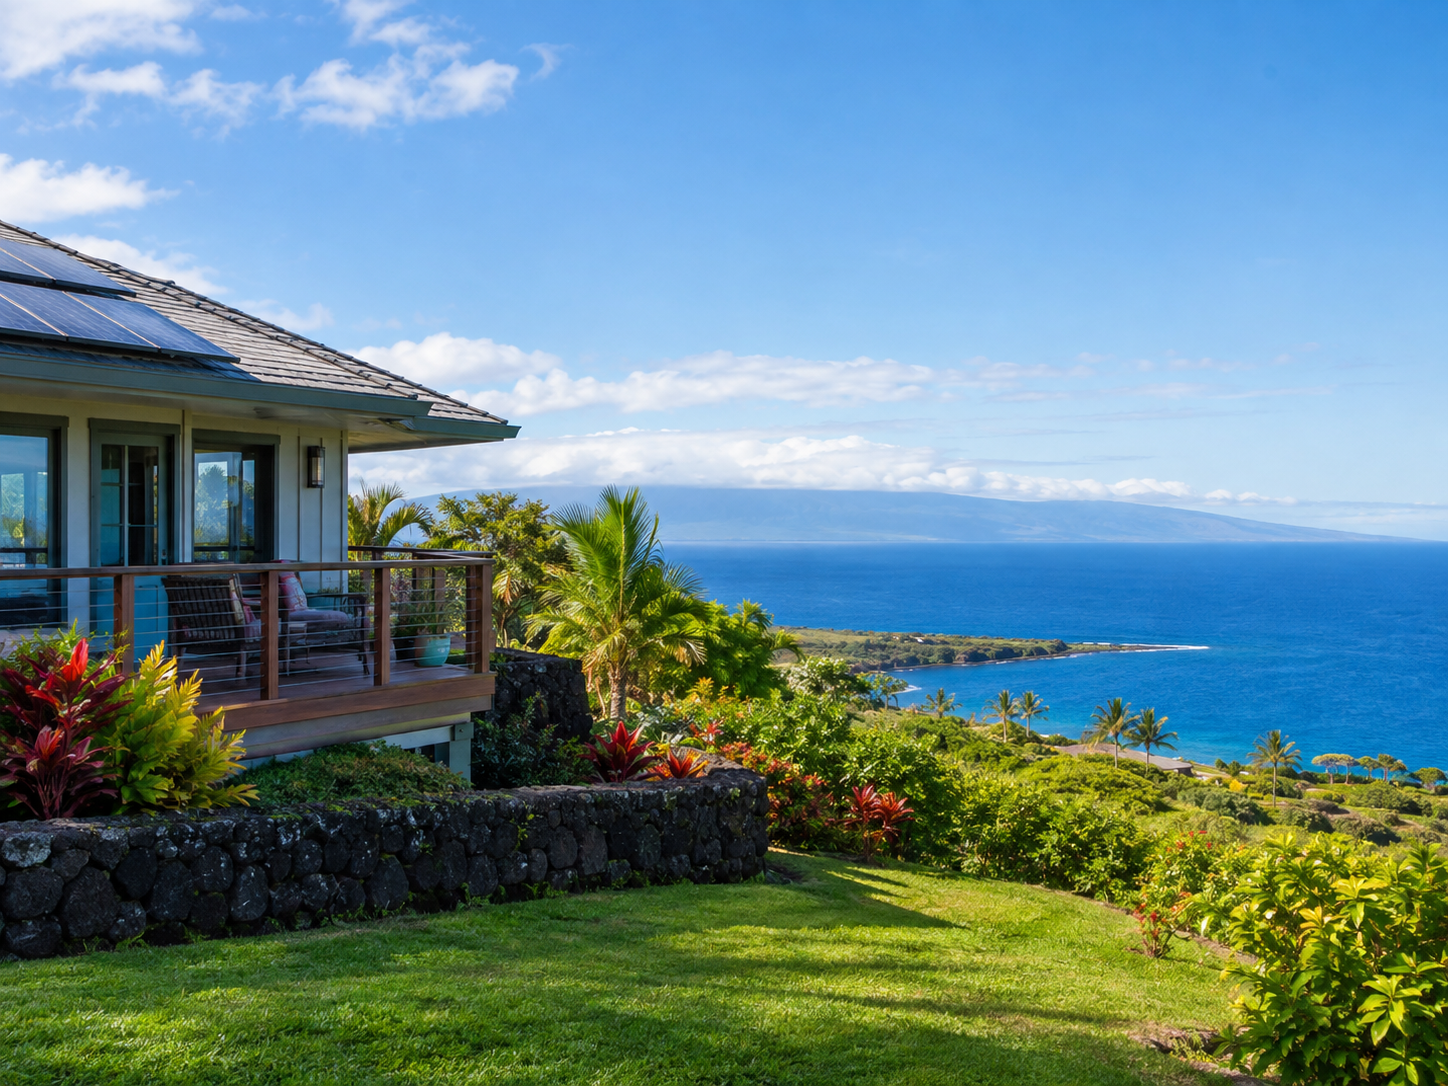
If your home has solar, have the documentation available showing whether the system is owned outright, financed, leased, or subject to a power-purchase agreement. Those distinctions can matter to both the appraisal and the lender.
Simply saying that a house “has solar” doesn’t tell the entire story. An owned photovoltaic system and a system governed by a third-party agreement are not necessarily treated the same way. Gathering the documentation before the property goes on the market can prevent questions later in the transaction.
Condition Will Be Documented in Greater Detail
UAD 3.6 also provides a more detailed description of property condition. Interior and exterior condition are addressed separately, and the new report captures more component-level information supporting the appraiser’s overall assessment.
That doesn’t mean every cosmetic imperfection reduces the appraised value, and it certainly doesn’t mean that every dollar spent before listing produces a dollar—or more—in additional value. But it does reinforce something I already tell sellers: take care of reasonable deferred maintenance before the home is appraised.
A leaking faucet, deteriorated exterior element, broken fixture, damaged flooring, or other visible maintenance problem may be relatively inexpensive to correct. Leaving a collection of those items unresolved can contribute to the overall picture of a property that hasn’t been well maintained.
The home is appraised as it exists on the effective date of the appraisal. Preparing it for that inspection deserves the same forethought you give to preparing it for buyers.
Documentation Matters
This does not mean handing the appraiser a sales pitch. Appraisers are independent, and neither the seller nor the real estate agent should try to dictate a value.
It does mean making accurate, relevant information readily available.
Before listing, I would want to assemble documentation for significant permitted improvements and additions; ʻohana units, ADUs, and other living areas; substantial renovations; photovoltaic systems and their ownership or financing arrangements; and other property characteristics that may not be obvious from a visual inspection or public records.
The objective isn’t to influence the appraisal. It is to reduce the possibility that an important characteristic of the property is misunderstood or overlooked.
What About the Timeline?
Appraisal capacity is another reason to allow adequate time. The appraisal profession has an aging workforce, and there is widespread concern within the industry about the additional work and learning curve associated with UAD 3.6. Some experienced appraisers have said they intend to retire or stop accepting Fannie Mae and Freddie Mac appraisal assignments rather than make the transition.
No one yet knows how many will actually do so or what the effect will be in individual markets. But there is another reason to take the timing concern seriously: appraisers themselves expect UAD 3.6 reports to take longer. In an August 2026 industry survey of 863 appraisers, more than three-quarters of those responding to the turnaround-time question anticipated longer turnaround times. That expectation remained almost as high among appraisers who had already completed UAD 3.6 reports.
That may be particularly relevant on Hawaiʻi Island, where the pool of appraisers is already limited and many properties require substantial local knowledge. I would not assume that every appraisal will take longer after November 2, but particularly during the transition, I would allow adequate time rather than build a transaction around an unnecessarily tight appraisal deadline.
A delayed appraisal can compress everything that follows: final underwriting, loan approval, preparation and signing of loan documents, and funding.
That matters in Hawaiʻi because our escrow process operates on a “good funds” basis. Closing occurs when the transaction records with the State of Hawaiʻi Bureau of Conveyances, and escrow needs cleared funds in advance of that recording. In practice, Hawaiʻi escrow companies commonly require good funds by 11:00 a.m. two full business days before the scheduled recording date.
Weekends and holidays can push that deadline considerably earlier. For example, a Tuesday closing following a Monday holiday can require funds to be in escrow the preceding Thursday.
That is why losing a day or two earlier in the transaction can sometimes cost considerably more than a day or two at the end. The appraisal is one of the financing milestones that can affect everything downstream, so I would rather build a realistic appraisal window into a Hawaiʻi purchase contract than assume there will be time to make up a delay later.
Does UAD 3.6 Change the Value of Your Home?
No. UAD 3.6 is a new appraisal reporting and data standard, not a new method for determining market value.
The appraiser still develops an independent opinion of value using appropriate appraisal methods and market evidence, including comparable sales. UAD 3.6 doesn’t make a home worth more or less. It provides a more detailed and standardized way to describe the property and support the appraiser’s analysis.
For Hawaiʻi Island sellers, I think that distinction is important. A property with an exceptional ocean view, a well-documented permitted ʻohana, substantial improvements, or an owned photovoltaic system doesn’t become more valuable simply because the new appraisal format describes those things more precisely. Their contribution to value still has to be supported by the market.
But describing the property accurately is the necessary first step.
What Should a Hawaiʻi Island Seller Do?
If you expect to sell after the new standard becomes mandatory, don’t wait until the appraiser is scheduled to start thinking about this.
Look at your property the way someone encountering it for the first time will have to understand it. Are the improvements properly documented? Do you know the status of additional living areas? Can you readily explain when significant renovations were completed? Do you have the paperwork for your photovoltaic system? Are there minor maintenance issues that should reasonably be addressed before listing?
None of this is about “gaming” an appraisal. It is simply good preparation for a system that will document the property in considerably greater detail. And on Hawaiʻi Island, where properties can be anything but standardized, good documentation may matter more than ever.
If you are thinking about selling and want a straightforward assessment of how your property may be viewed under the new appraisal format—including what you should document, what you might want to address before listing, and how much time to allow for the transaction—I’m glad to walk through it with you.
Text or call me at 808-769-0727, or email me at carol@betterislandlifestyle.com.
With aloha,
Carol Porter
REALTOR® · RS-87584 · HI · Better Homes and Gardens Real Estate Island Lifestyle
Next step
Questions about your own search?
Every situation is different, and the details change the answer. Tell me what you’re considering and I’ll give you an honest read.